 how-to
Is a Stair Lift Covered by Insurance?
Last Updated: October 29, 2026
Quick Summary
Is a stair lift covered by insurance? In most cases, no. Original Medicare generally treats stair lifts as non-covered home modifications, and private plans and Medicaid programs vary widely. Some programs may pay part of the cost when a doctor documents medical need, but coverage is never automatic.
- Original Medicare usually treats stair lifts as home modifications, so it generally does not pay for them.
- Medicaid may fund home modifications through HCBS waivers, with income limits and prior authorization.
- A doctor's prescription supports a claim but does not guarantee the insurer will pay.
- Ask your insurer whether stair lifts are classified as DME, a home modification, or an exclusion.
- If insurance denies coverage, check veterans benefits, state programs, and medical financing options.
Table of Contents
- Is a Stair Lift Covered by Insurance? The Short Answer
- Does Medicare Cover Stair Lifts?
- Does Medicaid Cover Stair Lifts Through Waiver Programs?
- Private Insurance Coverage for Stair Lifts
- Stair Lift Funding Options When Insurance Says No
- How to Check Your Coverage and Appeal a Denial
- Booking Your Stair Lift Consultation With CT Stairlifts
- Frequently Asked Questions
Is a Stair Lift Covered by Insurance? The Short Answer
Is a stair lift covered by insurance? In most cases, no. Original Medicare generally treats stair lifts as non-covered equipment, and private plans and Medicaid programs vary widely. Some programs may pay part of the cost when a doctor documents a medical need, but coverage is never automatic.
The answer depends on your insurer, your state, and your specific medical situation. Below are options to check first.
Watch out: Many people assume a doctor's prescription guarantees payment. It does not. A prescription supports a claim, but the insurer still decides whether the stair lift meets its rules.
Does Medicare Cover Stair Lifts?
Original Medicare does not generally pay for stair lifts, because it considers them home modifications rather than medical equipment. Medicare may cover some durable medical equipment, but stair lifts usually fall outside that category.
Why Original Medicare Usually Treats Stair Lifts as Non-Covered
Medicare covers equipment that is medically necessary and used in the home for a medical purpose (Durable Medical Equipment Coverage). A stair lift is often viewed as a convenience or home improvement. That distinction is why many claims are denied.
- Medicare focuses on medical necessity, not comfort
- Home modifications are generally excluded
- Coverage decisions depend on documentation from your doctor
Medicare Advantage Plans and Plan Variation
Medicare Advantage plans are offered by private insurers and can differ from Original Medicare. Some plans may include extra benefits for home safety equipment. Coverage varies by plan, so review your Summary of Benefits or call the plan directly before you buy.
Does Medicaid Cover Stair Lifts Through Waiver Programs?
Medicaid is a joint federal and state program, and coverage rules are set mostly at the state level (Medicaid). Some Medicaid programs fund home modifications through Home and Community-Based Services (HCBS) waivers. These waivers are designed to help people with disabilities or older adults stay at home rather than move into a facility.
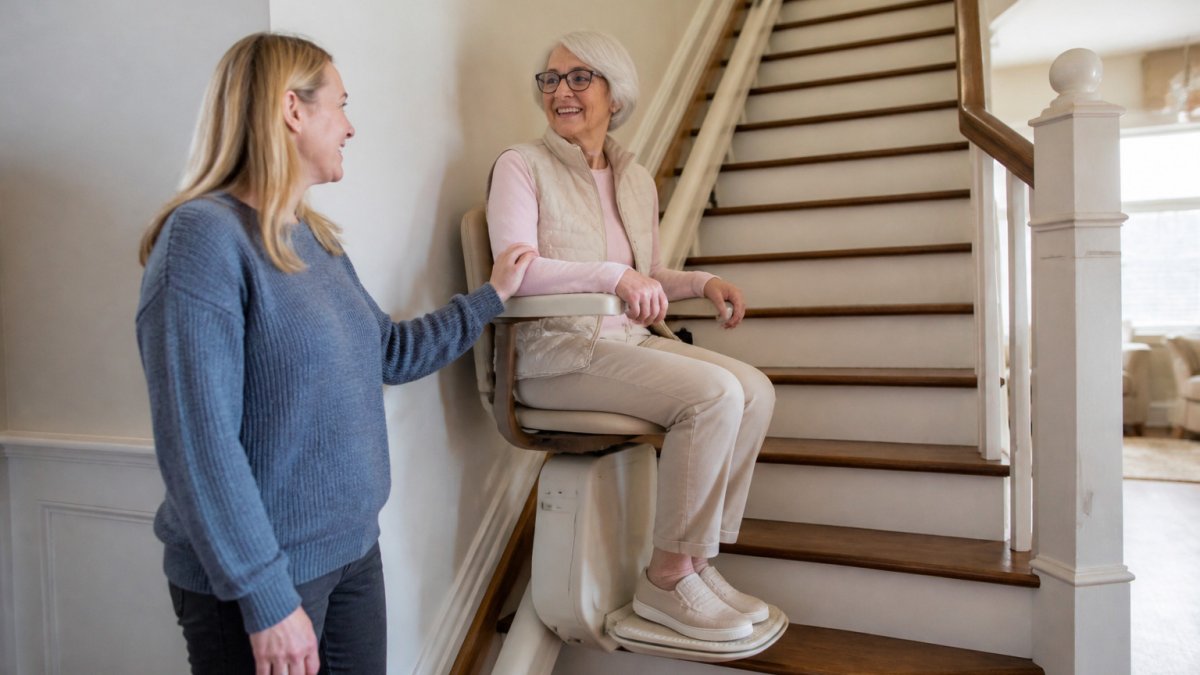
Eligibility usually depends on income, level of care needs, and whether the state has an approved waiver. Your state Medicaid office can tell you whether a stair lift is an allowed expense under its waiver program. Connecticut's program rules should be confirmed directly with the state's official Medicaid resources.
- Income and asset limits may apply
- A medical need must be documented
- Approval often requires a prior authorization process
Medicaid coverage for home modifications depends on state rules and waiver programs, so the key points are summarised below.
| Factor | What the article says | Note |
|---|---|---|
| Program type | HCBS waivers fund home modifications | Designed to keep people at home |
| Eligibility | Income, level of care, approved waiver | Varies by state |
| Income/asset limits | May apply | Check with state office |
| Medical need | Must be documented | Required for approval |
| Approval process | Often requires prior authorization | Confirm before purchase |
Private Insurance Coverage for Stair Lifts
Private health insurance plans set their own coverage rules, and stair lifts sit in an awkward category. Most plans draw a line between durable medical equipment (DME) and home modifications. A stair lift is permanently attached to the staircase, so many plans classify it as a home modification and exclude it, even when a doctor says it is medically necessary. A smaller number of plans treat a stair lift as DME or as an approved home-safety benefit, which is why coverage is rare but not impossible.
First, Confirm What You Are Asking About
Before you call your insurer, make sure you are asking about the right device. The rules differ by equipment type, and mixing them up is one of the most common reasons a request gets denied for the wrong reason.
- Stair lift: A chair or platform that carries a person up and down an existing staircase. Usually bolted to the treads or the wall.
- Lift chair: A recliner that tilts forward to help a person stand. This is furniture-like DME, not a stair device, and is sometimes covered under a different benefit.
- Wheelchair lift: A platform or hoist that raises a wheelchair, often at a vehicle or a porch. Vehicle lifts may fall under auto or mobility benefits, not home DME.
If your denial letter cites the wrong device category, ask the plan to correct the record before you appeal.
Questions to Ask Your Insurer
Call the member services number on your ID card and work through this list. Write down the representative's name, the date, and a reference number for the call.
- Does my plan cover durable medical equipment for use in the home? Ask for the exact policy section.
- Is a stair lift classified as DME, a home modification, or an excluded item under my plan?
- Is prior authorization required before purchase or installation?
- What documentation does the plan require, a physician's letter, a functional assessment, or both?
- Is there a coverage limit, a rental option, or a partial reimbursement rate?
- Are there in-network suppliers, and does the plan require me to use one?
- What is the appeal deadline if the request is denied?
What Documentation Usually Helps
Most practitioners find that a strong request package includes a letter from your physician stating the diagnosis, why you cannot safely use the stairs, and why the stair lift is the least costly option that meets the need. Pair that with any physical or occupational therapy notes and a description of your home's staircase. Keep copies of everything you send.
If your plan excludes home modifications outright, a private insurance claim is unlikely to succeed no matter how strong the documentation. In that case, move to the funding options below rather than spending months on an appeal that cannot change the plan's written exclusion.
Stair Lift Funding Options When Insurance Says No
If insurance does not pay, other stair lift funding options may still help. Many families use a mix of sources to cover the cost.
- Veterans benefits: The VA may offer grants or support for home accessibility for eligible veterans
- State and local programs: Some state agencies and nonprofits offer home modification assistance, and a step-by-step walkthrough of applying for stairlift grants shows how to request them.
- Medical financing: Some providers offer payment plans for home accessibility equipment
- Rental or used equipment: Renting can be a good fit for temporary needs, such as recovery from surgery
Contact your local Area Agency on Aging to ask about funding that may apply to your situation. Read the full guide to stairlift costs and aid options to see which programs might fit your case.
How to Check Your Coverage and Appeal a Denial
Most guides stop at "file an appeal." The practical work is in the steps around it: getting the denial in writing, understanding why it happened, and meeting the deadlines. This section walks through the full sequence so you are not guessing.
Step 1: Get the Decision in Writing
Ask your insurer or program for a written coverage determination. A phone answer is not enough. The letter should state the specific policy language or rule the decision relied on. If the letter only says "not covered," call back and ask for the cited policy section.
Step 2: Identify the Real Reason for the Denial
Denials usually fall into one of four buckets, and each needs a different response:
- Exclusion: The plan simply does not cover stair lifts or home modifications. Appeals rarely overturn a written exclusion; focus on other funding.
- Not medically necessary: The plan wants stronger proof of need. A more detailed physician letter and therapy notes are the fix.
- Documentation missing: A form, signature, or assessment was absent. Resubmit the complete package.
- Prior authorization skipped: The plan required approval before purchase. Ask whether retroactive authorization is possible.
Step 3: Meet the Appeal Deadline
Deadlines are set by your plan and by federal rules for certain plan types. The denial letter must state the deadline and the address or portal for filing. Missing it can end your options, so put the date on your calendar the day the letter arrives.
Step 4: File the Internal Appeal
Submit a written appeal that does three things: states what you are appealing, corrects the specific reason for the denial, and attaches the supporting records. Ask your physician to address the plan's stated reason directly rather than sending a generic letter.
Step 5: Request an External Review if Needed
If the internal appeal is denied, many plans allow an independent external review. The denial letter should explain how to request it and the deadline. This step is often overlooked, and it is the one most likely to change an outcome when the dispute is about medical necessity rather than a written exclusion.
Coverage Checklist
- Written coverage determination requested
- Denial reason and cited policy language identified
- Physician letter addressing the specific reason
- Therapy notes and functional assessment attached
- Prior authorization status confirmed
- Appeal deadline recorded
- Internal appeal filed with copies retained
- External review requested if internal appeal fails
- Every letter, form, and call reference number saved
How to Verify Coverage Before You Buy
Use the same questions whether you are dealing with a private plan, a Medicaid waiver, or a veterans program: What is covered, what documentation is required, is authorization needed first, and what is the appeal path? Getting those four answers in writing before you sign a contract is the single best way to avoid a surprise bill.
Booking Your Stair Lift Consultation With CT Stairlifts
If you are ready to explore your options, CT Stairlifts provides stairlift solutions designed to help individuals regain access to every floor of their home.
We recommend starting with a consultation so we can review your stairs, your mobility needs, and any coverage questions you have. CT Stairlifts offers a free home assessment to help you plan your next step. You can also get a stairlift installation quote to compare your options before making a decision.
Frequently Asked Questions
Will Medicare cover a wheelchair lift?
Original Medicare generally does not cover stair lifts or wheelchair lifts for home use because they are considered convenience or home modification items rather than durable medical equipment in most cases. Coverage can change depending on your medical records and the specific device. Medicare Advantage plans may offer different benefits, so check your plan's summary of benefits and ask whether a physician's prescription and documentation would change the decision. Confirm details directly with your plan or with Medicare at medicare.gov before you schedule an installation.
Can Medicaid pay for a stair lift?
Medicaid coverage for stair lifts varies by state and by program. Some states cover home modifications through Home and Community-Based Services waiver programs, and eligibility usually depends on income, level of care and medical need. Coverage is not guaranteed even when you qualify for Medicaid. Contact your state Medicaid agency in Connecticut to ask whether a waiver program covers stair lifts and what documentation it requires.
How do I find out whether my insurance covers a stair lift?
Start by requesting your plan's coverage guidelines for durable medical equipment and home modifications. Ask whether prior authorization is required and which documents, such as a doctor's prescription or medical records, the insurer needs. Get the answer in writing, including the reference number and the representative's name. Your physician can also help document how a mobility impairment affects your ability to use stairs safely.
What is the disadvantage of a stair lift?
The main drawbacks are cost and insurance coverage, which may be limited or unavailable.