 how-to
Stairlifts and Insurance: What's Actually Covered
Table of Contents
- Does Medicare Cover Stairlifts
- Does Medicaid Cover Stairlifts
- Private Insurance Coverage for Stairlifts
- Veterans Benefits and Other Assistance Programs
- How to Get a Free Stairlift
- Documentation and Eligibility Requirements
- Stairlift Costs and Coverage Verification Checklist
- Frequently Asked Questions
Last Updated: October 5, 2026
Does Medicare Cover Stairlifts
Original Medicare does not cover stairlifts, meaning stairlifts covered by insurance through Original Medicare is not an option. Medicare Part B covers durable medical equipment (DME) like wheelchairs, walkers, and oxygen tanks, but stairlifts fall into a different category. The program classifies stairlifts as home modifications rather than medical equipment, which is why they're excluded from coverage.
Some Medicare Advantage plans (Part C) do offer supplemental benefits that might cover stairlifts or similar accessibility equipment, so check your specific plan's details.
Medicare only covers portable or removable equipment; stairlifts are permanently installed and increase property value, so they don't qualify.
If you're on Original Medicare, explore Medicare Advantage plans with home modification benefits, Medicaid, private insurance, Veterans benefits, or other assistance programs.
Does Medicaid Cover Stairlifts
Medicaid coverage for stairlifts varies by state. Some states cover them as durable medical equipment or home modifications; others don't.
Many states cover stairlifts through Medicaid waiver programs designed to help people age in place, though eligibility and coverage limits vary.
Contact your state's Medicaid office to learn whether stairlifts are covered, what documentation is required, whether prior authorization is needed, and your cost-sharing responsibilities.
Requirements vary: some states require a doctor's prescription, others have income or asset limits, and some cover stairlifts only for specific conditions.
Your state's Medicaid program rules will have the definitive answer for your situation. Don't rely on general information, your state's specific rules are what matter.
Private Insurance Coverage for Stairlifts
Most private plans treat stairlifts as home modifications rather than durable medical equipment, but some offer supplemental coverage if a doctor prescribes it for medical necessity.
When private insurance may cover a stairlift:
Coverage succeeds when your plan includes home modifications or accessibility equipment, or when your doctor documents medical necessity. Examples: post-surgical recovery (hip replacement, spinal surgery), chronic conditions (arthritis, Parkinson's, MS), or documented mobility impairment.
The critical distinction is medical necessity versus home improvement. Document that the stairlift treats or prevents a medical condition; framing it as a convenience will likely result in denial.
Contact your insurer's benefits department and ask: (1) Does your plan cover DME? (2) Are home modifications covered when medically necessary? (3) Is prior authorization required? (4) What documentation proves medical necessity? (5) Are there supplemental riders for accessibility equipment? (6) What is the appeals process?
Ask your doctor to provide: a written prescription naming a stairlift, clinical notes on mobility limitations and fall risk, a statement explaining how it addresses your condition, and relevant diagnosis codes. Submit all documentation at once to avoid delays.
If denied, request a written explanation and file a formal appeal within 30-60 days. Include additional medical documentation, a letter from your doctor reiterating medical necessity, and your written explanation of the disagreement.
If denied, explore: HSA or FSA pre-tax dollars (check with HR), Medicaid or Medicare Advantage if eligible, or manufacturer financing plans (24-60 months).
Veterans Benefits and Other Assistance Programs
Veterans with service-connected disabilities may qualify for VA grants to cover stairlift installation through the Special Home Adaptation or Aid and Attendance programs.
Contact your local VA office or visit VA.gov for home modification benefits to learn about the Aid and Attendance benefit or the Special Home Adaptation grant. These programs specifically cover accessibility modifications like stairlifts.
Other assistance sources include nonprofits (disease-specific or aging-focused), state aging-in-place initiatives, manufacturer financing or rental programs, and community action agencies. Eligibility is limited and funding is often first-come, first-served, so start your search early.
How to Get a Free Stairlift
Most people pay for stairlifts through a combination of insurance coverage, financing, and out-of-pocket funds rather than a single free source.
Full or partial coverage options:
Medicaid waiver programs (state-dependent): If your state's Medicaid program covers stairlifts through a home modification or aging-in-place waiver, you may qualify for full or partial coverage with no out-of-pocket cost. Coverage varies widely by state. Contact your state Medicaid office or your local Area Agency on Aging to learn whether your state offers this benefit. States with known stairlift coverage in some waiver programs include California, New York, Florida, and Texas, though eligibility and benefit limits differ. Find your state Medicaid program
VA benefits (veterans only): Veterans with service-connected disabilities may qualify for grants through the Special Home Adaptation (SHA) program or Aid and Attendance benefit, which can cover the full cost of a stairlift. Eligibility depends on your service-connected disability rating and income. Contact your local VA office or VA Home Modifications Benefits to apply.
Nonprofits serving specific diseases (Parkinson's, ALS, stroke), aging-focused organizations, and community action agencies sometimes offer grants. These programs are limited, first-come-first-served, and have strict eligibility. Apply early to multiple programs.
Lower-cost alternatives to buying new:
Renting can be a sensible option for temporary needs (fewer than 12-18 months). Ask about rental-to-purchase options.
Used equipment: Buying a used stairlift can be a lower-cost alternative. Sources include:
- Online marketplaces (Facebook Marketplace, Craigslist, OfferUp)
- Stairlift retailers' used or refurbished inventory
- Estate sales and auctions
- Local disability equipment exchanges or nonprofits
When buying used, verify that the equipment works, ask about warranty coverage, and confirm that installation is included or budgeted separately. Used equipment may have limited or no warranty, so factor in potential repair costs.
Refurbished equipment from manufacturers: Some stairlift companies sell refurbished models. These are typically returned units that have been inspected, repaired, and tested. Ask your provider whether refurbished options are available.
Financing and payment plans:
While not free, financing makes a stairlift affordable by spreading the cost over time. Most stairlift providers offer:
- In-house financing: Payment plans
- Third-party financing: Companies like Affirm, CareCredit, or LendingClub offer medical equipment financing
- HSA or FSA funds: If you have a health savings account or flexible spending account through your employer, you can use pre-tax dollars to pay for a stairlift, which may reduce your out-of-pocket cost.
Combining sources for affordability:
Most people don't find a single free source. Instead, they combine:
- Medicaid or Medicare Advantage coverage for 50-100% of the cost
- A payment plan for any remaining balance
- Or: used equipment + financing for the installation
- Or: rental during recovery + purchase later if long-term need is confirmed
Action steps to find the most affordable option for you:
- Verify insurance coverage first. Contact your Medicaid office, Medicare Advantage plan, or private insurer to learn what they'll cover. This is your largest potential savings.
- Get multiple quotes. Contact at least two stairlift providers and ask for itemized pricing (equipment, installation, delivery, customization).
- Ask about all payment options. Inquire about rental, used equipment, refurbished models, and financing terms.
- Calculate total out-of-pocket cost. Subtract insurance coverage and any grants from the total quote to see your real cost.
- Explore HSA/FSA funds. If you have these accounts, using pre-tax dollars reduces your effective cost.
- Research state and local programs. Contact your Area Agency on Aging or local community action agency to ask about home modification grants or programs.
The most practical path to affordability is usually a combination: maximizing insurance coverage, choosing a financing option that fits your budget, and considering rental or used equipment if a new purchase is unaffordable.
Documentation and Eligibility Requirements
To qualify for stairlifts covered by insurance, you'll typically need medical documentation showing why the stairlift is necessary. This might include:
- A doctor's prescription or written recommendation
- Medical records showing your diagnosis or condition
- Documentation of mobility limitations or fall risk
- Proof that you meet your insurance plan's medical necessity criteria
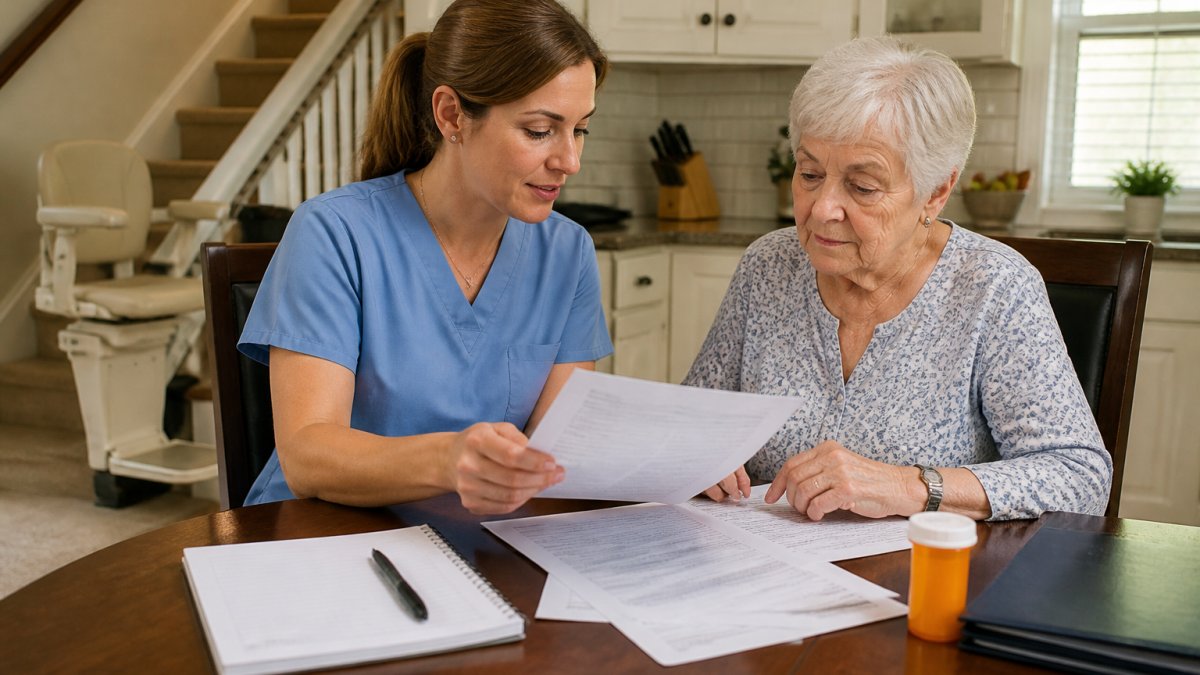
Different insurance programs have different requirements. Medicare Advantage plans may need a prescription from your doctor. Medicaid programs vary by state but often require similar documentation. Private insurance typically requires proof of medical necessity.
Start by scheduling a consultation with your doctor. Explain that you're considering a stairlift and ask whether they'd recommend one for your specific condition. If they agree it's medically necessary, ask them to document this in writing.
Once you have medical documentation, contact your insurance company or state program to understand their specific approval process. Many programs require prior authorization before installation. Submitting incomplete paperwork delays the process, so ask for a checklist of required documents upfront.
Keep copies of everything you submit. If your claim is denied, you'll need these documents to file an appeal.
Stairlift Costs and Coverage Verification Checklist
Understanding stairlift costs helps you plan your budget and explore coverage options effectively. Costs vary based on the type of stairlift, your home's configuration, and installation complexity.
| Factor | Impact on Cost | What to Consider |
|---|---|---|
| Stair type | Straight stairs cost less | Curved stairs require custom installation |
| Installation complexity | Simple installations cost less | Tight spaces or narrow stairs increase cost |
| New vs. used equipment | Used equipment costs significantly less | Check condition and warranty carefully |
| Rental vs. purchase | Rentals are cheaper short-term | Purchasing is better for long-term needs |
| Delivery and setup | Varies by provider | Ask about included vs. additional fees |
Before you commit to purchasing or renting, verify your coverage options:
Step 1: Check your insurance eligibility
- Contact your insurance company or state Medicaid office
- Ask whether stairlifts are covered in your plan
- Request documentation of coverage rules and any limitations
Step 2: Gather medical documentation
- Schedule a doctor's visit if you haven't recently
- Ask your doctor whether a stairlift is medically necessary for your condition
- Request written documentation of the medical need
Step 3: Submit for prior authorization (if required)
- Many insurance programs require approval before installation
- Submit all required documentation at once
- Ask for a timeline for the approval decision
Step 4: Get quotes from providers
- Contact at least two stairlift providers for pricing
- Ask about financing options and payment plans
- Clarify what's included in the installation price
Step 5: Compare total out-of-pocket costs
- Calculate your cost after insurance coverage
- Factor in any deductibles or co-pays
- Ask about rental options if you're uncertain about long-term need
Step 6: File your claim or request
- Follow your insurance company's submission process
- Keep copies of all paperwork
- Track approval status and follow up if needed
Taking time to verify coverage before purchasing saves money and frustration. Many people discover coverage options only after they've already paid out of pocket.
Navigating stairlift coverage can feel overwhelming, but breaking it down by program makes it manageable. Start by identifying which insurance program you're on, Medicare, Medicaid, private insurance, or Veterans benefits, then contact that program directly to understand your specific coverage rules and eligibility requirements. At CT Stairlifts, we help homeowners understand their options. Whether you're exploring coverage or ready to move forward, our team can answer your questions about stairlift solutions designed to help you regain access to every floor of your home safely and independently.
Frequently Asked Questions
Does Medicare pay for stairlifts?
Original Medicare (Parts A and B) does not cover stairlifts as a standalone purchase. However, Medicare Part B may cover stair lifts in limited cases if your doctor prescribes one as durable medical equipment and it meets strict medical necessity criteria. Medicare Advantage plans vary by carrier and may offer additional coverage. Contact your plan directly to confirm whether stairlifts are covered under your specific benefit structure.
Does Medicaid cover stairlifts?
Medicaid coverage for stairlifts varies significantly by state. Some state Medicaid programs cover stairlifts as home modifications or durable medical equipment if medically necessary, while others do not. Your state's Medicaid agency determines eligibility and coverage limits. Contact your state Medicaid office or visit its official website to learn whether stairlifts are covered and what documentation you need to apply.
What documentation do I need to request stairlift coverage?
Most insurance programs require a doctor's prescription or recommendation stating medical necessity, a diagnosis supporting the need for a stairlift, and documentation of your mobility impairment or activities of daily living limitations. Some programs also require a home assessment or occupational therapist evaluation. Check with your specific insurance provider or state program to confirm exact documentation requirements before submitting a claim.
What should I do if my insurance claim for a stairlift is denied?
Request a written explanation of the denial from your insurance company. Review your plan documents to understand the appeal process and deadlines. Gather additional medical evidence, such as a letter from your doctor emphasizing medical necessity or a home safety assessment. File a formal appeal within the timeframe specified by your plan, and consider asking your healthcare provider to advocate on your behalf during the appeal process.